
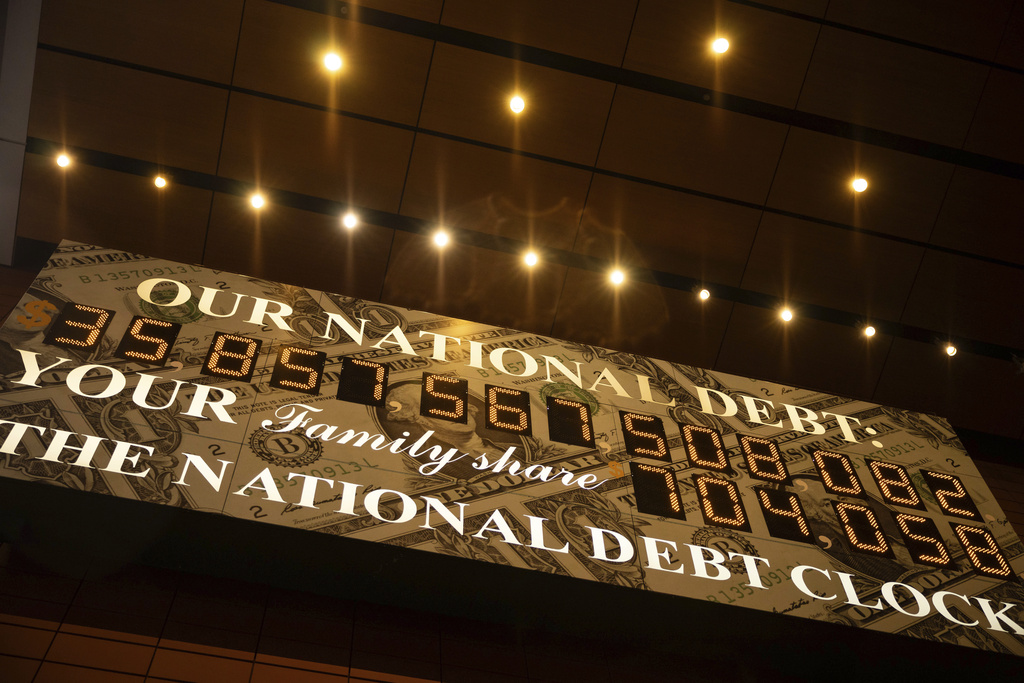
The U.S. national debt has reached $40 trillion, pushing the conversation beyond cost-cutting measures. The core issue is that spending cuts alone will not bridge the gap. The focus must shift toward increasing revenue.
Medicare expenses, projected at $1 trillion for fiscal 2026, illustrate the challenge. Even eliminating Medicare, a move seen as politically infeasible, would cover only half the current deficit. Social Security costs, predicted at $1.7 trillion and growing, further complicate matters.
Many suggest cutting what they view as “wasteful” spending from domestic federal agencies. However, dissolving these agencies would address just 13–14 percent of the federal budget.
Mandatory spending accounts for a majority of the budget, with Social Security, Medicare, and Medicaid alone costing about $5.6 trillion. Discretionary spending, which Congress votes on, covers about $2.0 trillion, primarily defense and other categories often labeled “waste.” In addition, servicing the debt will cost approximately $1.1 trillion in fiscal 2026.
Debt-held interest rates surpass 3.3 percent, with current rates up to 1.3 points higher. Refinancing debt under higher rates will increase the interest bill by nearly $100 billion. A significant revenue source is essential.
Introducing a VAT emerges as the sole credible solution. This tax impacts value added at each production stage and keeps necessities like food and clothing exempt to reduce regressive impacts. Although it raises prices, its structure ensures it is hidden in goods’ prices rather than added at purchase.
The Congressional Budget Office estimates a 5 percent VAT could generate $350 billion in 2027, growing to $440 billion by 2034. A 10 percent rate promises to cut the primary deficit by $1.3 to $1.6 trillion yearly, even after accounting for GDP effects.
Among European nations, VAT rates average 21 percent, making a proposed 10 percent U.S. rate competitive. To manage its regressive nature, necessities can remain exempt from VAT, and a rebate system like Canada’s GST credit can support low-income households.
Peter J. Tanous underscores the urgency of action. “Do nothing, and we risk a financial and stock market crisis eclipsing 2008–2009,” he explains. The numbers underscore the need for Congressional movement.
Tanous serves as chairman emeritus at Lynx Investment Advisory and has authored impactful works on investment and prosperity.